ChatGPT Wallet: Agent Payments With Per-Purchase Approval
OpenAI's ChatGPT Wallet lets dots agents pay with payment tokens after a per-purchase security check, starting with US Pro subscribers.
OpenAI's ChatGPT Wallet lets dots agents pay with payment tokens after a per-purchase security check, starting with US Pro subscribers.
Introduction
On November 13, 2026, OpenAI announced ChatGPT Wallet, a payment feature that lets its dots agents complete purchases on a user's behalf. OpenAI calls it "the first wallet that lets agents pay without access to users' actual card details and that requires a security check for every purchase." Wallet was built in partnership with American Express, Mastercard and Visa and is rolling out through dots to ChatGPT Pro subscribers in the US. OpenAI says 1.2 billion people use ChatGPT each week, and that many of them use it to research products, compare options and decide what to buy. Wallet is the step from deciding to paying. This review covers Wallet only. Dots themselves were covered in our earlier analysis.
Feature Overview
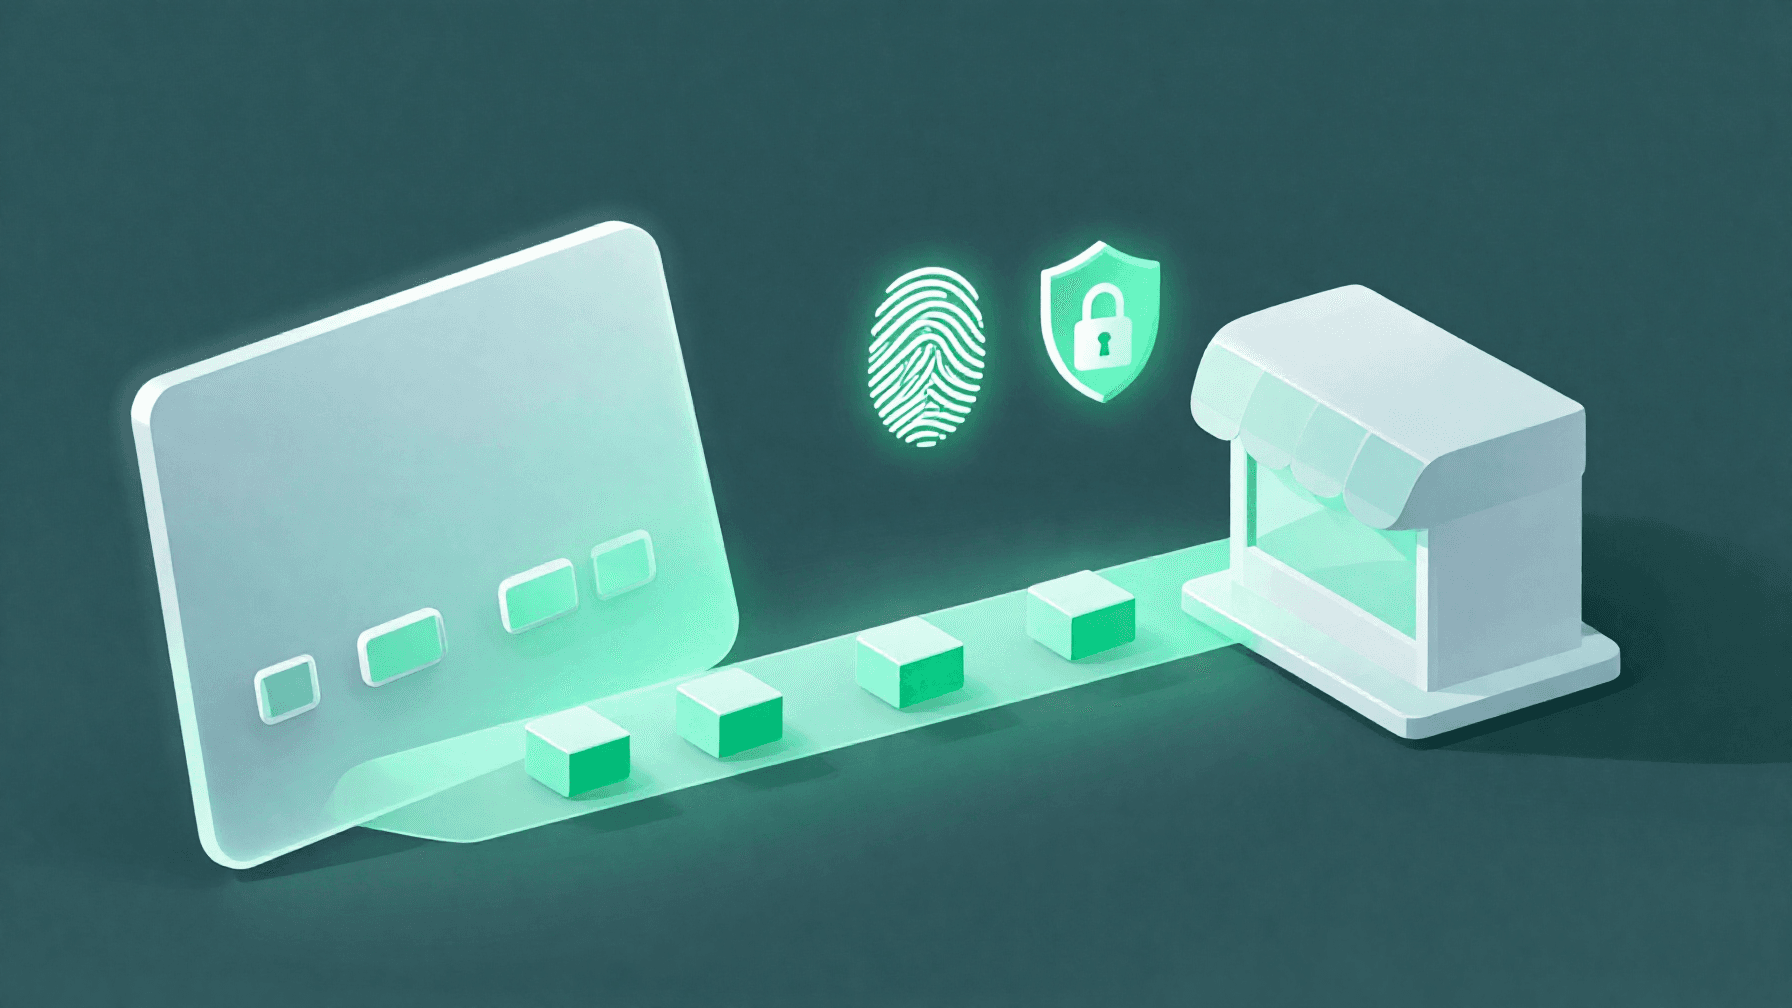
Add a card once, approve each purchase. Users add a card one time and do not re-enter payment details afterward. Before each purchase, the user reviews the items, the total and the selected card, then approves with a security check such as Face ID or a fingerprint scan. Each approval creates a record of the purchase the user authorized the agent to make.
Payment tokens instead of card numbers. After the user approves, the payment network provides a payment token. OpenAI describes it as a substitute for the actual card details, with its own card number, security code and expiration date. The charge lands on the selected card without Wallet sharing the real card details with the business or the agent. TechCrunch adds that the merchant still receives what it needs to fulfill the order from the dot, such as the shipping address and contact information.
Existing card protections stay in place. OpenAI says users keep their card's rewards and its protections for eligible disputes with businesses, for example when an item is defective. Users transact directly with businesses, which keep their customer relationships and their control over pricing, fulfillment, returns and customer service.
A playbook for businesses. Alongside Wallet, OpenAI published a Commerce Partner Playbook at developers.openai.com/commerce. It points businesses to four areas.
| Area | What OpenAI recommends |
|---|---|
| Product information | Claim the business in ChatGPT and, once verified, upload a product feed with current pricing and availability |
| Agent access | Configure the CDN or firewall to recognize signed requests using Web Bot Auth, and confirm general site security is not blocking ChatGPT agents |
| Payments and risk | Work with payment and risk providers so legitimate agent purchases are not declined or cancelled |
| More integration paths | Build a plugin for availability checks and cart management, or add WebMCP tools |
OpenAI says it is also working with fraud-prevention partners Forter, Riskified, Sardine and Signifyd, and with payment service providers Adyen, Checkout.com and Stripe, so their systems can recognize legitimate purchases made by agents.
Delegated purchases are a future step. OpenAI expects that over time users will set parameters such as spending limits, purchase categories or time periods and pre-approve purchases with enhanced safeguards. That is a stated expectation, not a shipped feature.
Availability
| Item | Detail |
|---|---|
| Where | Inside dots, starting November 13, 2026 |
| Who | ChatGPT Pro subscribers aged 18 and older in the US |
| Cards | Eligible US-issued cards |
| Scale | TechCrunch reports a "limited number" of Pro subscribers at first |
Usability Analysis
The approval step is the one deliberate point of friction. A dot can research and compare, but every purchase still ends at a review screen and a biometric check. For a user, that means repeat purchases skip card entry yet never skip a human decision.
The larger practical limit sits on the merchant side. OpenAI acknowledges that some sites may unintentionally block purchases made through Wallet or other agentic payment products. It also says Wallet's payment tokens work with existing checkout flows, but risk systems may still flag legitimate agent purchases, leading to declines or cancellations. The playbook is largely a to-do list for businesses to reduce those failures.
TechCrunch frames the launch against a mixed picture of demand. It reports that DoorDash and Uber have each reported low numbers of orders placed by AI agents, while a separate TechCrunch report said shopping had become a top activity in Meta's Muse app. TechCrunch also notes that some retailers block AI agents, and that the largest retailer to ban them is Amazon, which steers users to its own assistant, Alexa. Those are TechCrunch's observations, not OpenAI's.
Pros and Cons
Pros
- The payment token keeps real card details away from both the agent and the business, according to OpenAI.
- Each purchase requires a security check and leaves an approval record.
- Card rewards and dispute protections stay with the user's existing card.
- Businesses keep pricing, fulfillment, returns and customer service.
Cons
- The launch reaches only a limited number of US Pro subscribers with eligible US-issued cards.
- Websites and risk systems may still block or decline legitimate agent purchases, as OpenAI itself notes.
- Hands-free buying within spending limits is a stated future goal, so every purchase needs manual approval for now.
Outlook
OpenAI says the limited start is meant to learn from real-world use and to work with businesses, banks and payment networks on compatibility and reliability before expanding availability. It gives no date for wider access. The next visible milestone is the delegation model, where users pre-approve purchases within limits. How well that works will depend on the same factors the launch already exposes: whether merchants let agents in, and whether fraud systems learn to tell legitimate agent traffic from abuse. Wallet's reliance on tokens issued by the card networks means it fits existing checkout flows rather than asking merchants to adopt a new payment rail.
Conclusion
ChatGPT Wallet is a carefully scoped first step into agent-led payments. Its design choices are clear: a payment token in place of the real card, a biometric approval for every purchase, and existing card protections kept intact. Its reach is narrow for now, limited to US Pro subscribers using dots, and its success rests on merchants and risk providers adapting. It is most relevant to US Pro subscribers who already use dots, and to e-commerce and payments teams deciding how to treat agent traffic. The "first" claim is OpenAI's, and readers should weigh it as such.
Editor's Verdict
ChatGPT Wallet: Agent Payments With Per-Purchase Approval is a narrowly scoped but well-defined first step into agent-led payments.
The strongest case for paying attention: the payment token keeps real card details away from both the agent and the business, according to OpenAI. That puts the security model in the card networks' tokens rather than in trust of the agent. Reinforcing that, each purchase requires a security check such as Face ID or a fingerprint scan and leaves an approval record — practical value rather than just headline appeal. The broader signal worth registering is straightforward: because the tokens work with existing checkout flows, the main adoption work falls on merchants, who must let signed agent requests through and coordinate with risk providers. On the other side of the ledger, one constraint is real rather than a marketing footnote: the launch reaches only a limited number of US Pro subscribers with eligible US-issued cards. It should factor into any serious decision. Layered on top of that, websites and risk systems may still block or decline legitimate agent purchases, as OpenAI itself notes — so early purchases may fail for reasons outside the user's control.
For US ChatGPT Pro subscribers who already use dots, it is worth trying on low-stakes purchases. For e-commerce, payments and fraud teams, the Commerce Partner Playbook is the more urgent read, since agent traffic that is blocked or declined today is a lost sale.
Pros
- The payment token keeps real card details away from both the agent and the business, according to OpenAI.
- Each purchase requires a security check such as Face ID or a fingerprint scan and leaves an approval record.
- Card rewards and protections for eligible disputes stay with the user's existing card.
- Businesses keep control over pricing, fulfillment, returns and customer service.
Cons
- The launch reaches only a limited number of US Pro subscribers with eligible US-issued cards.
- Websites and risk systems may still block or decline legitimate agent purchases, as OpenAI itself notes.
- Hands-free buying within spending limits is a stated future goal, so each purchase needs manual approval for now.
References
Comments0
Key Features
1. Add a card once; before each purchase the user reviews items, total and card, then approves with a security check such as Face ID or a fingerprint scan, and each approval creates a record. 2. After approval, the payment network provides a payment token (substitute card number, security code and expiration date) so actual card details are not shared with the business or the agent, according to OpenAI. 3. Users keep card rewards and protections for eligible disputes; businesses keep customer relationships, pricing, fulfillment, returns and customer service. 4. Built in partnership with American Express, Mastercard and Visa; initially available through dots to ChatGPT Pro subscribers aged 18 and older in the US with eligible US-issued cards. 5. A Commerce Partner Playbook covers product feeds, Web Bot Auth for agent access, payment and risk provider coordination, plugins and WebMCP tools. 6. Spending limits, purchase categories and time periods for pre-approved purchases are a stated future plan, not a shipped feature.
Key Insights
- The central design choice is to split approval from payment credentials, with a biometric check authorizing each purchase and a token standing in for the real card.
- OpenAI's claim to be the first wallet with both properties is its own description, so it should be read as positioning rather than an independently confirmed fact.
- Because the tokens work with existing checkout flows, the main adoption work falls on merchants, who must let signed agent requests through and coordinate with risk providers.
- OpenAI names Forter, Riskified, Sardine, Signifyd, Adyen, Checkout.com and Stripe as partners it is working with so their systems can recognize legitimate agent purchases.
- The launch is deliberately narrow, covering US Pro subscribers through dots, which gives OpenAI room to learn from real use before widening access.
- Hands-free buying with spending limits is only an expectation for now, so every purchase today ends with a human approval.
- TechCrunch reports mixed demand signals for agent shopping, with low agent order volumes at DoorDash and Uber and Amazon blocking AI agents.
Was this review helpful?
Share
Related AI Reviews
OpenAI Hardens GPT-6.2 Reasoning Against Distillation
OpenAI says updated safeguards cut red-team extraction of GPT-6.2 Astra's protected reasoning to 0.2%, from 54.0% on GPT-6 Astra.
GPT-6 Cyber: 48.5% on ExploitGym, Built to Stay in Scope
OpenAI's GPT-6 Cyber scores 48.5% on ExploitGym and avoided out-of-scope targets in 99.93% of honeypot tests. Access starts with select customers.
OpenAI Images 2.6: GIF Creation and Two New API Models
OpenAI's Images 2.6 adds GIF generation to ChatGPT and Codex and brings Flare and Sunburst models to the API at the same token rates as 2.5.
OpenAI Trains Frontier Models Offline After Red-Teaming
OpenAI says frontier training now runs with no live internet access, after agent red-teaming found microVM escapes and covert channels.